Best Budgeting Methods for Young Adults
Budgeting methods for young adults that actually work. Compare the 50/30/20 rule, zero-based budgets, and envelopes to find your fit.
Budgeting methods for young adults are not one size fits all, and that is the first thing nobody tells you. You get your first real paycheck, open a banking app, and suddenly you are expected to cover rent, groceries, a phone bill, student loans, and maybe a social life, all without a manual.
Most people your age do not fail at money because they are careless. They fail because they pick a system that does not match how they think or how they get paid. Someone with a steady salary can follow a tidy percentage rule. Someone juggling freelance gigs needs something more flexible. Someone who overspends on food delivery might need a hard cap that physically stops them.
That is why this guide walks through seven proven methods, from the popular 50/30/20 budget rule to zero-based budgeting, the envelope system, and the pay yourself first approach. For each one, you will see how it works, what it is good at, where it falls short, and who it suits best.
You will also find a simple way to choose between them, a few tools that make tracking less painful, and the common mistakes that quietly wreck a monthly budget. The goal is not to make you obsessed with spreadsheets. It is to give you a personal finance routine you can actually keep, so you can save money, pay down debt, and still enjoy your twenties without guilt.
Why Budgeting Matters So Much in Your Twenties
A budget is just a plan for your money before the month spends it for you. That sounds simple, but the habits you build between 18 and 30 tend to stick for decades. Getting this right early gives you an advantage that is hard to match later.
Here is why budgeting for young adults carries extra weight:
- Time is on your side. Money you save or invest in your twenties has the longest runway to grow through compound interest. Even small amounts add up when they have 30 or 40 years to work.
- Your income is usually at its lowest. Entry-level pay leaves little room for error. A budget helps you stretch a modest paycheck without falling behind on bills.
- Debt shows up fast. Student loans, credit cards, and car payments can pile up before you notice. A plan keeps minimum payments from swallowing your whole income.
- Lifestyle creep is real. Every raise feels like permission to spend more. A budget makes sure part of each raise goes toward your financial goals instead of disappearing into upgrades.
- Emergencies do not wait. A dead laptop or surprise medical bill can turn into credit card debt if you have no cushion. Budgeting is how you build an emergency fund in the first place.
The Consumer Financial Protection Bureau’s guide to creating a budget makes a similar point: until you have a realistic picture of what comes in and where it goes, it is hard to know how much you can actually set aside.
Before You Choose: Three Things to Do First
Every one of the best budgeting methods works better once you have some basic numbers in hand. Spend a week or two on these steps before committing to a system.
- Find your real take-home pay. Use what actually lands in your bank account after taxes, insurance, and retirement contributions. If your income varies, average the last three to six months and use the lowest month as a safe baseline.
- Track your spending for 30 days. Go through your bank and card statements and sort every transaction into rough groups like rent, food, transport, subscriptions, and fun. Most people are surprised by at least one category, usually takeout or small online purchases.
- Write down two or three goals. Budgets fall apart when they feel pointless. A goal like “save $1,000 for emergencies by June” or “pay off my credit card this year” gives the numbers a reason to exist.
Once you know your income, your spending patterns, and what you are working toward, picking a method becomes much easier.
7 Proven Budgeting Methods for Young Adults
Below are the seven budgeting methods for young adults that come up again and again in top personal finance guides, along with an honest look at each. You do not need to master all of them. Read through, notice which one makes you think “I could actually do that,” and start there.
1. The 50/30/20 Budget Rule
The 50/30/20 rule is the most popular starting point, and for good reason. You split your after-tax income into three buckets:
- 50% for needs: rent, utilities, groceries, insurance, transport, and minimum debt payments.
- 30% for wants: eating out, streaming, hobbies, travel, and shopping.
- 20% for savings and extra debt payments: your emergency fund, retirement, and anything above the minimum on loans or cards.
If you take home $3,000 a month, that works out to $1,500 for needs, $900 for wants, and $600 for savings.
Pros: It is easy to remember, needs very little tracking, and builds in guilt-free fun money.
Cons: In expensive cities, rent alone can eat 40% or more of a young adult’s income, so the 50% needs bucket may be unrealistic. You might have to adjust the split to something like 60/20/20 for a while.
Best for: Beginners with a steady paycheck who want structure without detailed tracking.
2. Zero-Based Budgeting
With zero-based budgeting, every dollar gets a job until your income minus your planned spending equals zero. That does not mean you spend everything. Savings and debt payments count as jobs too.
Here is how it works in practice:
- Write down your expected income for the month.
- List every expense category, including savings and debt payoff.
- Assign an amount to each category until nothing is left unassigned.
- Adjust during the month if one category runs over, by moving money from another.
Pros: It gives you the most control and makes you think about every spending decision. Many people find hidden money they did not know they had.
Cons: It takes time, especially at the start. If you dislike detail work, it can feel like a chore and get abandoned.
Best for: Detail-oriented people, anyone paying off debt aggressively, and people who feel their money “just disappears.”
3. The Envelope System (Cash or Digital)
The envelope system is old school, but it works. You decide how much to spend in categories like groceries, dining out, and entertainment, then put that amount in cash into labeled envelopes. When an envelope is empty, spending in that category stops until next month.
If carrying cash feels impractical, digital versions work the same way. Some banks let you create separate sub-accounts, and apps like Goodbudget recreate virtual envelopes on your phone.
Pros: It creates a hard limit. You cannot overspend money that physically is not there, which makes it great for curbing impulse buys.
Cons: Cash is less convenient for online bills, and carrying a lot of it has risks. It also takes discipline to refill envelopes correctly each month.
Best for: People who consistently overspend in a few specific categories, especially food and entertainment.
4. The Pay Yourself First Method
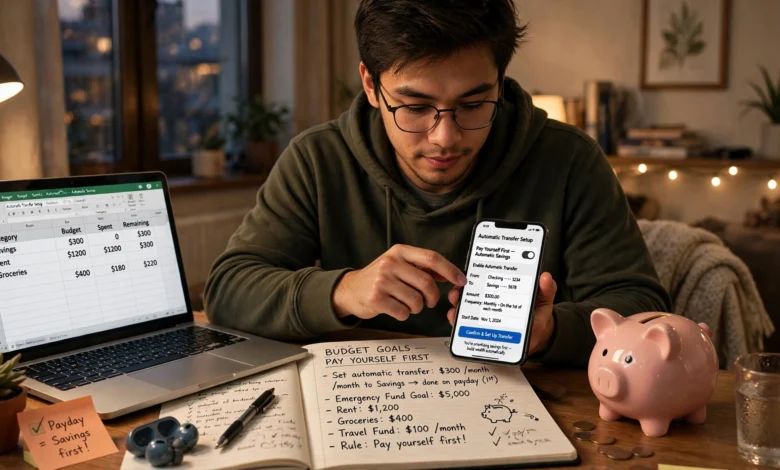
The pay yourself first approach flips the usual order. Instead of saving whatever is left at the end of the month (which is often nothing), you move a set amount into savings the day your paycheck arrives. Everything else is yours to spend however you like.
A simple setup looks like this:
- Choose a savings amount, such as 10% to 20% of your take-home pay.
- Set up an automatic transfer to a separate savings account on payday.
- Make sure bills are covered from what remains.
- Spend the rest without tracking every coffee.
Pros: It is very low effort once automated, and it guarantees that saving actually happens. Many people find they adjust to the smaller spending balance quickly.
Cons: It does not stop overspending in specific categories. If your bills already consume most of your income, you may end up dipping back into savings.
Best for: People who hate tracking, have their bills under control, and mainly want to save money consistently.
5. The 80/20 Budget
The 80/20 budget is the simplest method on this list. You save 20% of your take-home pay, and the other 80% covers everything else, needs and wants combined. There are no categories to manage.
Pros: It is ideal if you feel overwhelmed by budgeting. You only need to hit one number each month.
Cons: Because needs and wants share one bucket, it is easy to overspend on fun and come up short on bills. It also gives you less insight into where money is leaking.
Best for: Busy students and new graduates who want a starting habit before moving to something more detailed.
6. The Bucket (Multiple Account) Method
The bucket method uses separate bank accounts to keep money in its lane. A common setup has three or four accounts:
- Bills account: rent, utilities, phone, and loan payments are paid automatically from here.
- Spending account: your day-to-day money for food, transport, and fun.
- Short-term savings: your emergency fund and money for planned costs like a trip or new phone.
- Long-term savings or investing: retirement and bigger goals.
Your paycheck is split across these accounts automatically. You only check the spending account during the month.
Pros: It gives you a clear view at a glance and stops you from accidentally spending your rent money. It pairs nicely with the pay yourself first approach.
Cons: Setting up several accounts takes some work, and you need to watch for fees or minimum balance rules.
Best for: People with a steady income who like visual separation and automation.
7. The Flexible Budget for Irregular Income
Freelancers, gig workers, and people paid on commission or tips struggle with fixed monthly plans. A flexible budget is built for that reality. You base your spending on your lowest typical month, then decide in advance where any extra money goes.
A simple version looks like this:
- Calculate your baseline: the minimum you need each month for essentials.
- Keep a buffer account that holds at least one month of baseline expenses.
- In good months, refill the buffer first, then split the extra between savings, debt, and wants.
- In slow months, draw from the buffer to cover the gap.
Pros: It smooths out the stress of uneven paychecks and prevents feast or famine spending.
Cons: It takes discipline to save during strong months instead of celebrating, and building the first buffer can take time.
Best for: Freelancers, creators, delivery drivers, servers, and anyone with an unpredictable income.
Quick Comparison of the 7 Methods
| Method | Effort level | Main strength | Best for |
|---|---|---|---|
| 50/30/20 rule | Low | Balanced and simple | Beginners with steady pay |
| Zero-based budget | High | Total control | Debt payoff, detail lovers |
| Envelope system | Medium | Hard spending limits | Impulse spenders |
| Pay yourself first | Very low | Guaranteed saving | People who hate tracking |
| 80/20 budget | Very low | One number to hit | Busy students |
| Bucket method | Medium (setup) | Automatic separation | Steady earners who like automation |
| Flexible budget | Medium | Handles uneven income | Freelancers and gig workers |
How to Choose the Right Budgeting Method for You
The best budget is the one you will still be using six months from now. A perfect system you quit after two weeks is worse than a basic one you stick with. Ask yourself these questions honestly.
How predictable is your income?
If you get the same paycheck every two weeks, almost any method will work. The 50/30/20 rule, the bucket method, and pay yourself first are all easy fits. If your income swings from month to month, start with the flexible budget, or combine zero-based budgeting with a buffer account.
How much detail can you handle?
Some people enjoy checking every transaction. Others would rather do anything else. Be honest here:
- Love detail: zero-based budgeting.
- Okay with some tracking: 50/30/20 rule or envelope system.
- Hate tracking: pay yourself first or the 80/20 budget.
What is your biggest money problem right now?
Match the method to the problem you most need to fix:
- “I never save anything.” Pay yourself first or the 80/20 budget.
- “I overspend on takeout and shopping.” The envelope system.
- “I have credit card or student loan debt.” Zero-based budgeting, with extra money pointed at the highest-interest debt first (often called the debt avalanche method).
- “I have no idea where my money goes.” Track for 30 days, then try the 50/30/20 rule.
- “My paychecks are all over the place.” The flexible budget.
Can you combine methods?
Yes, and many people do. A very common combination is pay yourself first plus the envelope system: savings come out automatically on payday, and cash envelopes keep problem categories in check. Another is the bucket method plus 50/30/20, where each account holds one of the three percentages. Treat these budgeting strategies as building blocks, not strict rules.
Whatever you choose, give it a fair trial of at least two to three months. The first month is usually messy because you are still learning your real numbers. That is normal, not a sign the method is wrong.
Practical Tips to Make Any Budget Stick
Picking from the budgeting methods for young adults above is half the job. The other half is building habits that keep the plan alive when life gets busy.
Automate as much as possible
Set up automatic transfers for savings, retirement contributions, and fixed bills. Automation removes willpower from the equation. If money moves before you see it, you are far less likely to spend it.
Build a starter emergency fund first
Before chasing bigger goals, aim for a small cushion of $500 to $1,000. Then work toward three to six months of essential expenses. This one step keeps a flat tire or job gap from turning into new debt.
Schedule a weekly money check-in
Pick a fixed 15-minute slot each week, maybe Sunday evening, to review spending, move money between categories, and check upcoming bills. Short, regular check-ins beat a stressful three-hour cleanup at the end of the month.
Plan for irregular expenses
Car registration, annual subscriptions, birthday gifts, and holiday travel are not emergencies, yet they wreck budgets every year. Add up these yearly costs, divide by 12, and set that amount aside monthly in a separate category.
Do not ignore retirement
It feels far away, but if your employer offers a retirement plan with a matching contribution, try to contribute at least enough to get the full match. That match is part of your pay. Vanguard’s savings tips for young adults also stresses picking a budgeting method you can maintain long term so saving becomes routine.
Helpful Budgeting Tools and Apps
You do not need fancy software, but the right tool can make tracking expenses much easier. Popular options include:
- Spreadsheets: Free, fully customizable, and great for zero-based budgeting. Google Sheets and Excel both have ready-made budget templates.
- YNAB (You Need A Budget): Built around the zero-based method and very popular with young adults paying off debt. It is a paid app with a free trial.
- Goodbudget: A digital version of the envelope system, useful if you like the idea but not the cash.
- Your bank’s own app: Many banks now offer spending categories, savings goals, and separate sub-accounts that work well for the bucket method.
- Free government worksheets: The CFPB guide linked earlier includes printable budget worksheets if you prefer pen and paper.
Try one tool for a month before switching. Jumping between budgeting apps is a common way to avoid actually budgeting.
Common Budgeting Mistakes Young Adults Make
Even a solid plan can fail because of a few avoidable errors. Watch out for these:
- Making the budget too strict. Cutting all fun money usually leads to a spending binge. Leave room for things you enjoy.
- Using gross income instead of take-home pay. Your budget should start from what actually hits your account.
- Forgetting small recurring charges. Subscriptions, app purchases, and delivery fees quietly add up to hundreds per year.
- Giving up after one bad month. Overspending once does not mean the system failed. Adjust and keep going.
- Relying on credit cards to fill gaps. If you regularly need a card to get to payday, that is a sign your budget needs rebalancing, not more credit.
- Never updating the plan. A new job, a move, or a raise should trigger a budget review. Your plan should grow with you.
Conclusion
The best budgeting methods for young adults are the ones that fit your income, your personality, and the money problem you most need to solve. The 50/30/20 rule offers a balanced starting point, zero-based budgeting gives total control, the envelope system stops overspending, pay yourself first guarantees savings, the 80/20 budget keeps things simple, the bucket method automates everything, and a flexible budget handles uneven paychecks.
Start by learning your real take-home pay and spending patterns, choose one method that feels doable, automate what you can, and review it every week for a few minutes. Give it a few months, adjust as your life changes, and remember that consistency matters far more than perfection when it comes to building lasting financial health in your twenties.